By Xavier Lugaga
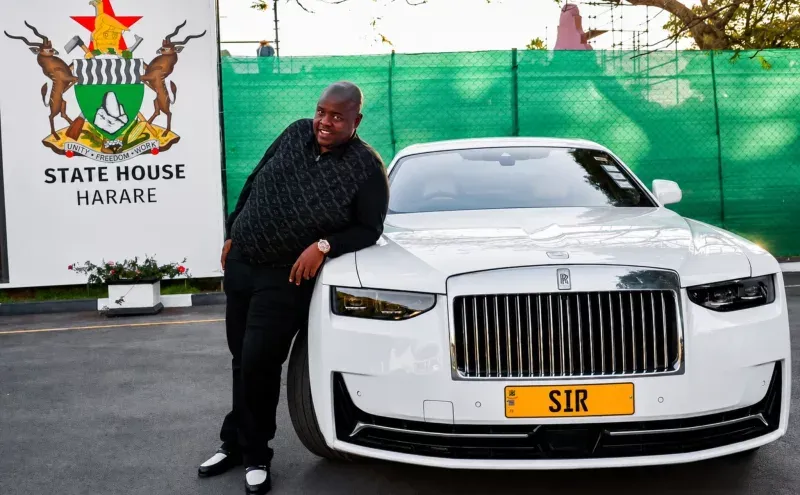
Being broke is painful. But being broke and determined to convince everybody that you are rich can be even more financially dangerous.
Because poverty, however uncomfortable, can be confronted. Pretence is different.
Pretence can become a lifestyle. And once the lifestyle is financed through loans, credit cards, mobile loans, overdrafts, chama borrowing, salary advances and money borrowed from friends and relatives, the problem stops being merely about appearances.
It becomes a financial trap.
In Kenya, where social media has turned lifestyles into public performances, the pressure to look successful can sometimes become stronger than the desire to actually become financially stable.
You have KSh1,500 in your bank account.
But your Instagram says:
“Soft life. God did it.”
You have three loans running.
But you are upgrading your phone because:
“Siwezi onekana na hii ya zamani.”
Rent is pending.
School fees is pending.
Your emergency fund is zero.
But somehow there is money for nyama choma every weekend.
Why?
“Watu wakiona tuko na stress watatuonaje?”
That question captures a growing financial dilemma: are we living for ourselves, or are we spending money to manage other people's perception of us?
THE PROBLEM IS NOT BEING POOR
There is absolutely no shame in experiencing a difficult financial season.
People lose jobs.
Businesses collapse.
Farmers experience failed seasons.
Salaries delay.
Medical bills appear unexpectedly.
Children need school fees.
Parents need support.
Rent rises.
Fuel prices fluctuate.
A family can therefore find itself financially squeezed even when its members are hardworking and responsible.
Being temporarily broke does not mean someone is lazy, foolish or unsuccessful.
Sometimes life simply becomes expensive.
What matters is what happens next.
There are Kenyans going through difficult financial periods who are making remarkably sensible decisions.
They cook at home.
They use older phones.
They postpone expensive holidays.
They wear clothes they already own.
They use public transport.
They drive affordable cars.
They negotiate debts.
They reduce unnecessary subscriptions.
They save whatever little they can.
They contribute to their chamas.
They invest in farms, businesses, education or cooperative societies.
Most importantly, they are building.
There is dignity in that.
THE DANGER STARTS WHEN APPEARANCE BECOMES A FINANCIAL PRIORITY
Imagine someone earning KSh50,000 a month. After rent, food, transport, school fees, utilities and other obligations, perhaps KSh7,000 remains.
That KSh7,000 could become the beginning of an emergency fund. It could reduce debt.
It could help purchase farm inputs.
It could support a small side business.
It could contribute to a Sacco.
It could simply remain untouched as a financial buffer.
But then a friend posts photographs from Diani.
The beach.
The hotel.
The swimming pool.
The sunset.
The seafood.
The caption:
“Life is for the living.”
And suddenly the KSh7,000 feels inadequate.
“Sisi pia tunafaa.”
A KSh30,000 loan is obtained.
The holiday happens.
The photographs are taken.
Instagram is updated.
Friends comment:
“Boss!”
“Mambo ni moto!”
“Wewe umeomoka!”
For 48 hours, everything looks perfect.
Meanwhile, the bank account is asking a very different question:
“Are we paying this loan, or are we also going to Diani?”
That is where the joke ends.
SOCIAL MEDIA HAS CREATED A NEW KIND OF POVERTY
There is traditional poverty: lacking sufficient resources to meet basic needs.
Then there is what might be called performative prosperity—spending beyond one's means in order to communicate a particular social status.
The second can be difficult to detect because photographs conceal financial reality.
A person may post a new vehicle without mentioning that the vehicle is heavily financed.
A restaurant photograph may conceal the debt behind the meal.
A designer outfit may have been purchased on credit.
A luxurious apartment may consume an unreasonable percentage of the person's income.
A holiday may have been financed by a mobile loan.
The photograph shows the destination.
It does not show the repayment schedule.
THE PHONE THAT BECOMES A FINANCIAL STATEMENT
Consider the smartphone.
There is nothing wrong with wanting a good phone.
But the problem begins when the phone becomes a status certificate.
Someone's current phone works perfectly.
The camera works.
WhatsApp works.
Mobile banking works.
Emails work.
Calls work.
But a new model arrives.
Suddenly the old phone becomes embarrassing.
“Siwezi tembea na hii mbele ya watu.”
So another debt is created.
The irony is powerful.
You are using an expensive phone to access a banking application that is showing you have no money.
You are using a premium device to check a balance of KSh1,500.
Technology has advanced.
But the financial position has not.
THE CAR TRAP
Cars provide another example.
There is a legitimate reason to own a vehicle.
Transport to work may require one.
A family may need it.
A business may depend on it.
But purchasing a vehicle primarily to impress neighbours can become expensive.
The purchase price is only the beginning.
There is fuel.
Insurance.
Servicing.
Tyres.
Repairs.
Parking.
Licensing.
Loan repayments.
Depreciation.
A person may therefore appear financially successful while quietly transferring a large proportion of monthly income into maintaining that appearance.
Meanwhile, the emergency fund remains empty.
“PEOPLE WILL TALK”
This is one of the most expensive sentences in personal finance.
“People will talk.”
People will talk if you rent a modest house.
They will talk if you use public transport.
They will talk if you repeat clothes.
They will talk if you postpone a holiday.
They will talk if you drive an older car.
They may even talk if you say you cannot afford something.
But here is the uncomfortable truth:
The people you are trying to impress will rarely pay your bills.
When the landlord demands rent, Instagram followers do not pay.
When a child is sent home for school fees, Facebook friends do not automatically clear the balance.
When a bank loan falls due, your WhatsApp status cannot negotiate the repayment.
When an emergency occurs, photographs cannot become cash.
FARMERS UNDERSTAND THIS BETTER THAN MOST
Consider a Kenyan farmer.
After harvesting maize, the farmer receives money.
There is enormous temptation to celebrate.
A new phone.
A new television.
A weekend in town.
Expensive clothes.
A motorcycle.
A vehicle.
Drinks.
A big party.
But another farmer may make a different calculation.
Part of the money goes toward school fees.
Another portion goes toward farm inputs.
Another goes into savings.
Another goes into a cooperative or Sacco.
Another remains available for emergencies.
The second farmer may not look as successful on social media.
But six months later, when the next planting season arrives, the difference becomes visible.
One has photographs.
The other has productive assets.
COOPERATIVES CAN BE PART OF THE SOLUTION
Kenya's cooperative movement has historically provided a mechanism through which people pool resources, save and access credit.
For farmers, Saccos and cooperatives can provide structured avenues for saving and financing—although members still need to understand the terms, risks and repayment obligations attached to borrowing.
The principle is simple: Credit should ideally help build capacity, not merely finance appearances.
Borrowing to purchase productive equipment, expand a business or invest in an income-generating activity is fundamentally different from borrowing simply to maintain an image.
Not every productive investment succeeds, of course.
But there is an important distinction between debt that supports an economic plan and debt that exists primarily to impress an audience.
THE WEALTHIEST-LOOKING PERSON MAY NOT BE THE WEALTHIEST PERSON
This is where appearances become particularly misleading.
A person with a modest car may have substantial savings.
A farmer wearing an old jacket may own several acres.
A teacher living in a simple house may have educated all their children and accumulated retirement savings.
A civil servant using an old smartphone may have quietly invested in land.
A small business owner who rarely posts photographs may have a healthy cash-flow position.
Meanwhile, someone displaying luxury every weekend may be financing the lifestyle through debt.
Wealth is not the same thing as consumption.
Consumption is visible.
Net worth often isn't.
Savings are invisible.
Debt can be invisible.
Financial discipline is rarely photographed.
THE KENYAN “SOFT LIFE” QUESTION
There is nothing inherently wrong with enjoying life.
A holiday is not a crime.
Eating nyama choma is not financial irresponsibility.
Buying a good phone is not necessarily foolish.
Driving a good car is not automatically reckless.
The issue is whether the spending is compatible with one's financial circumstances.
The same KSh30,000 holiday can mean completely different things to two people.
For one person, it may represent a small portion of accumulated disposable income.
For another, it may represent a high-interest loan that will take months to repay.
The photograph looks identical.
The financial consequences are completely different.
WHAT IF WE NORMALISED SAYING “I CAN'T AFFORD IT”?
Imagine a Kenya where saying: “I can't afford that right now.” was not interpreted as failure.
Imagine someone saying: “I'll travel next year.” “I'll buy that phone when I can afford it.”
“I'll finish paying my debts first.”
“I'll save before I upgrade.”
“I'll drive this car for another five years.”
There is tremendous financial power in those sentences.
Because every time you refuse unnecessary spending, you are effectively telling your future self:
“I choose financial stability over temporary applause.”
THE REAL FLEX
The real flex may not be a new phone.
It may be having six months of essential expenses saved.
It may be clearing a high-interest loan.
It may be paying school fees on time.
It may be owning productive land.
It may be having a thriving farm.
It may be running a profitable small business.
It may be contributing consistently to a Sacco.
It may be having insurance.
It may be being able to handle an emergency without borrowing.
It may be retiring without depending entirely on your children.
None of these things necessarily produces an impressive Instagram photograph.
But they can produce something far more valuable: financial resilience.
SO, WHICH IS MORE DANGEROUS?
Being poor—or going through a difficult financial season—is painful.
But being financially stretched while deliberately maintaining an expensive image can compound the problem, because it adds unnecessary spending and debt to an already difficult situation.
The solution is not to stop enjoying life.
It is to stop confusing looking wealthy with becoming financially secure.
There is nothing embarrassing about rebuilding.
There is nothing shameful about using an old phone.
There is nothing humiliating about postponing a holiday.
There is nothing backward about using public transport.
There is nothing shameful about cooking at home.
There is nothing wrong with telling friends:
“Leo sina budget.”
Sometimes the most sophisticated financial decision is simply refusing to spend money you do not have.
Because eventually, the applause stops.
The photographs disappear into the archive.
The Instagram story expires after 24 hours.
The holiday ends.
The nyama choma is eaten.
The new phone becomes old.
But the loan remains.
Don't spend your future trying to impress people who may not even remember what you posted yesterday.
Build quietly.Save consistently.
Invest carefully.
Pay your debts.
Support your family.
Grow your income. And when the time comes to enjoy the fruits of your work, enjoy them without having to borrow money to prove that you are doing well.
Looking rich is a performance.
Building financial security is a process.
And the two should never be confused.Start writing your story…
No comments yet. Be the first to share your thoughts.